Quick answer: Bilt lets you pay your mortgage through its app with no transaction fee and earn up to 1.25 points per dollar. A $2,500 monthly mortgage earns 30,000 points a year at 1 point per dollar, or 37,500 at 1.25.
Your mortgage is probably the biggest check you write every month — and until this year, it earned you exactly zero points. Renters have had the Bilt card since 2021, racking up transferable points on rent with no fees. Homeowners watched from the sidelines. That changed in February 2026 with the launch of Bilt Card 2.0: mortgages now earn points too, a first for the U.S. credit card industry.
Here’s how it works, what it actually earns a family, and the catches worth knowing before you move your mortgage over.
The three cards
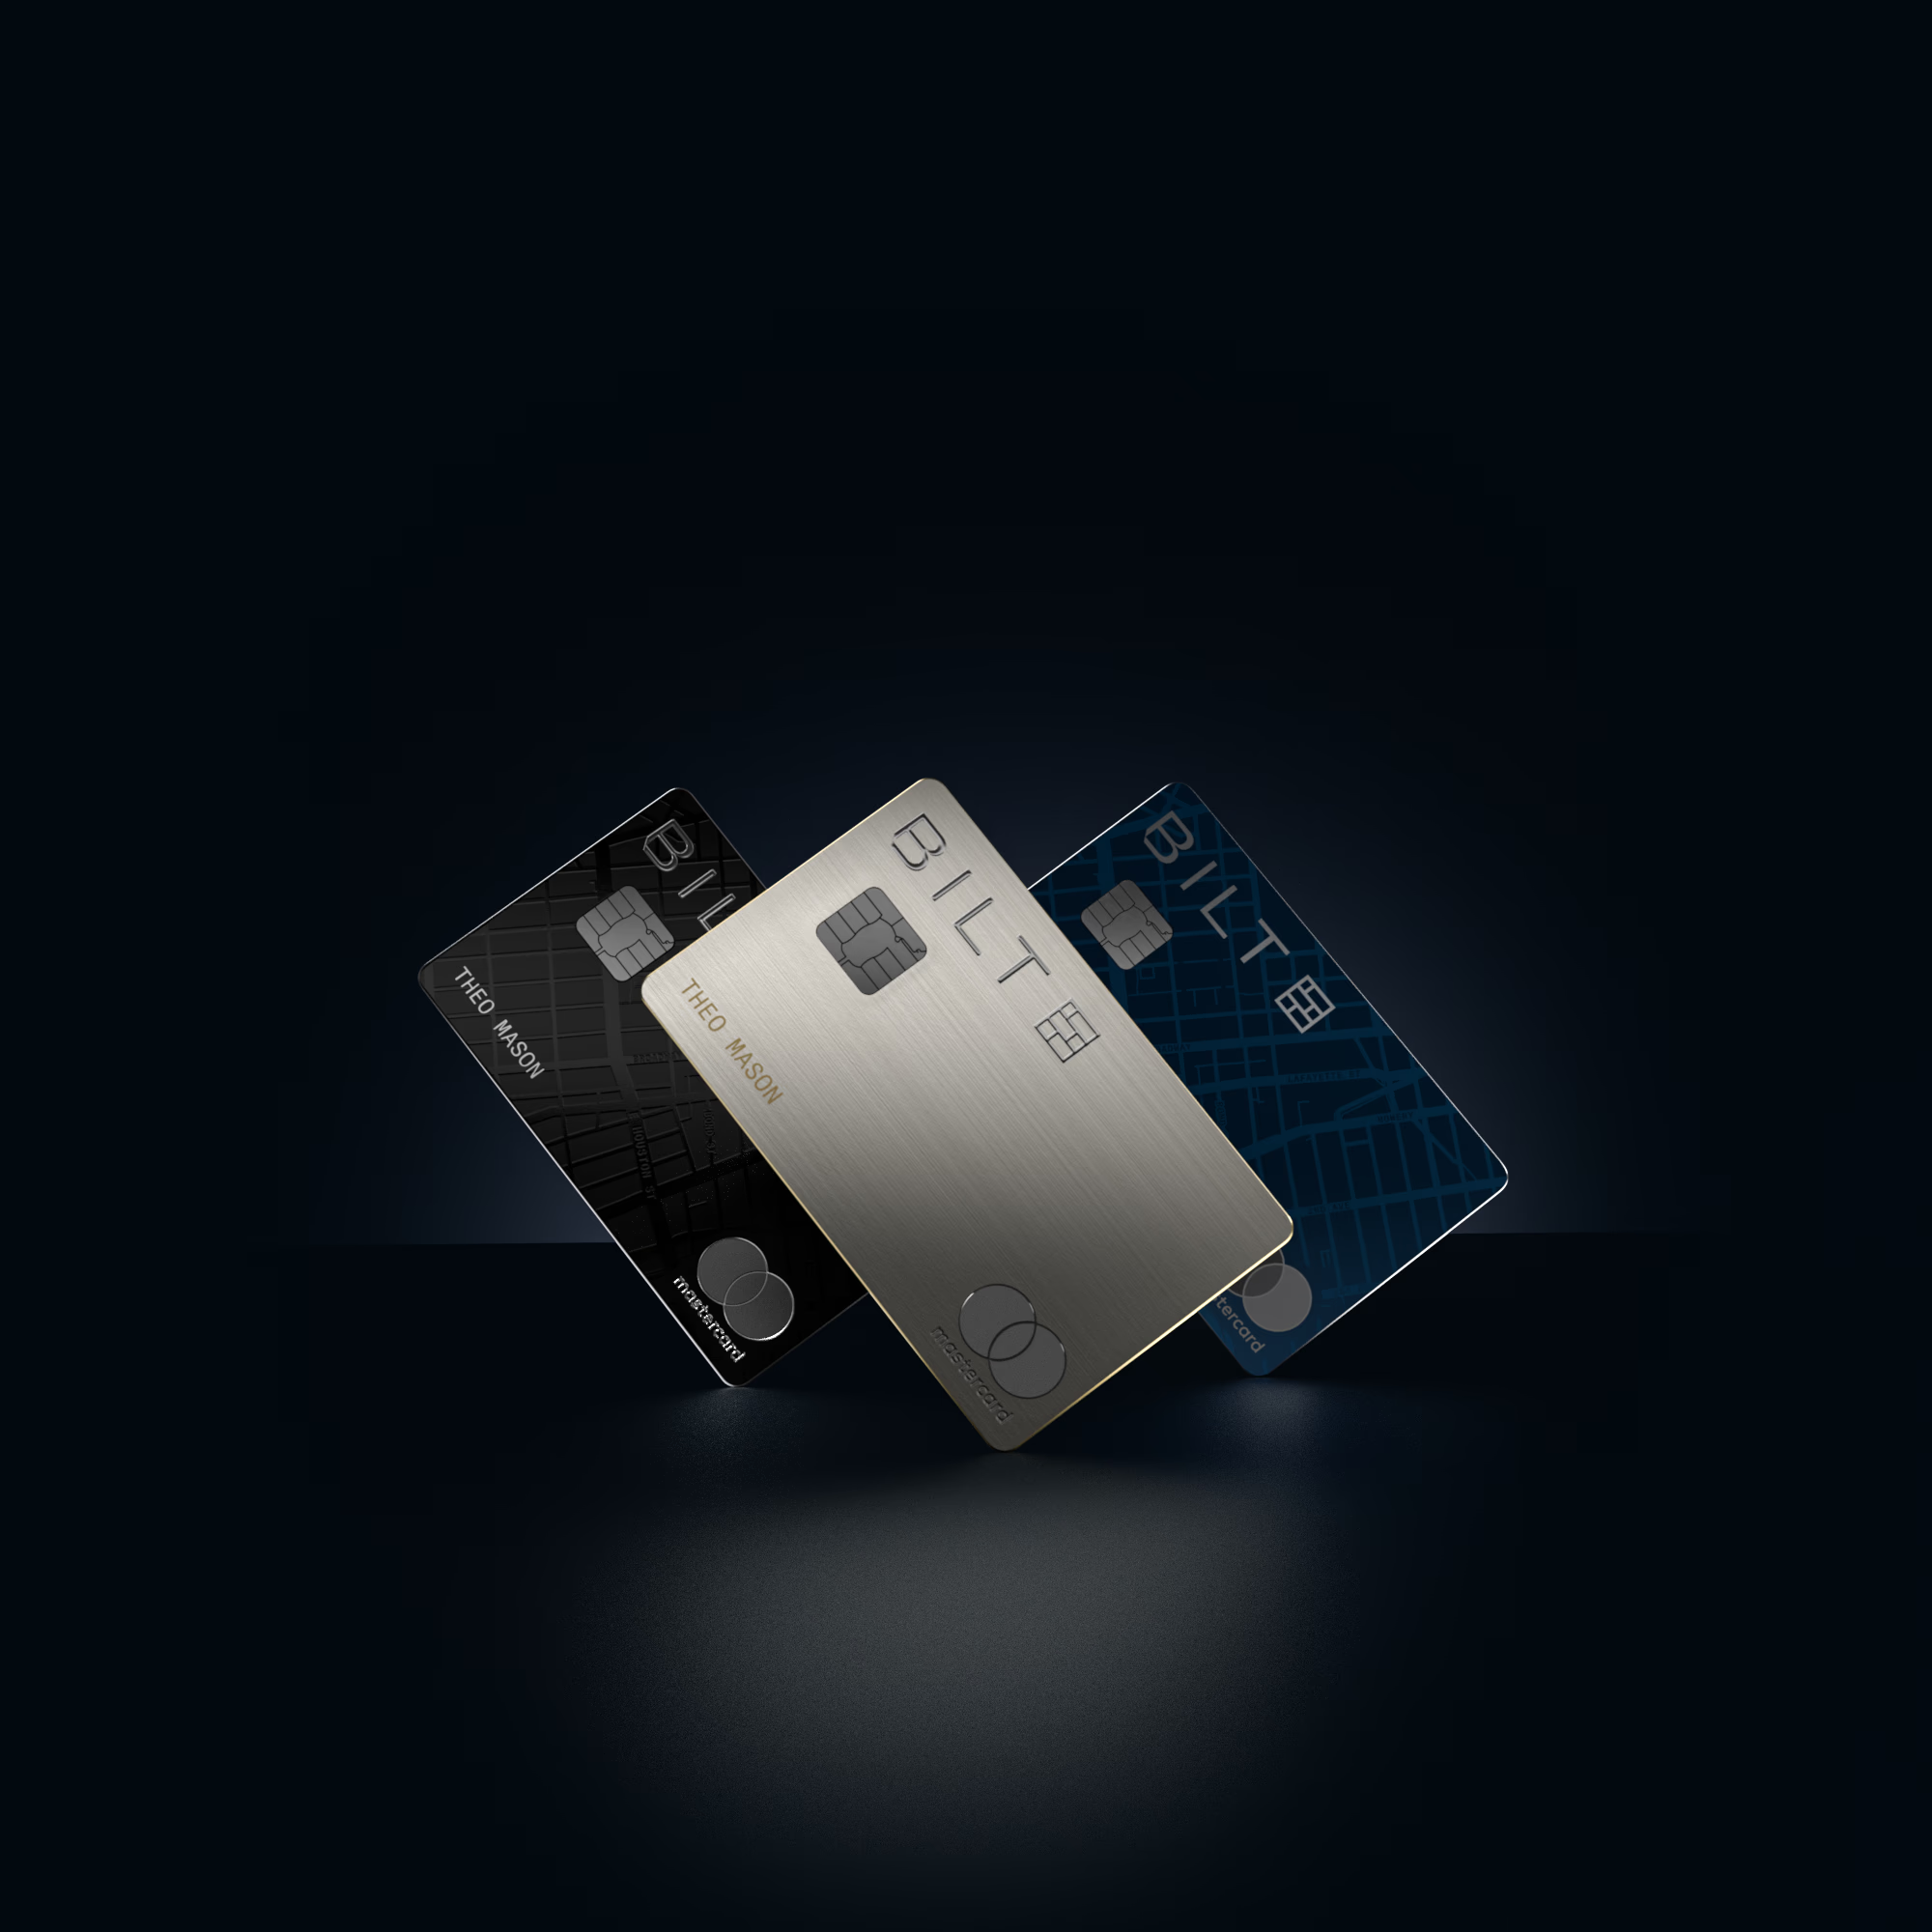
Bilt split from Wells Fargo and relaunched with three tiers, all issued through Cardless:
- Bilt Blue — $0 annual fee. 1x points on everyday spend, up to 1x on rent/mortgage.
- Bilt Obsidian — $95 annual fee. 3x on dining or groceries (up to $25k/year), 2x on travel, 1x everything else, up to 1x on rent/mortgage.
- Bilt Palladium — $495 annual fee. 2x on everyday spend, up to 1.25x on rent/mortgage, plus Priority Pass, hotel credits, and a 50,000-point welcome bonus.
All three let you pay rent and mortgage with no transaction fee through the Bilt app — that’s the whole game. Paying a mortgage with any normal credit card either isn’t possible or costs ~3% in processing fees, which wipes out the rewards.
How the points actually work (two paths)
Bilt 2.0 gives you a choice:
Path 1 — Housing-focused: Earn up to 1.25x points per dollar on your rent or mortgage, with the exact rate tied to how much everyday spending you put on the card.
Path 2 — Bilt Cash: Earn 4% back in Bilt Cash on everyday spending, then redeem it toward housing payments — every $30 of Bilt Cash redeemed earns 1,000 Bilt points, up to 1x of your monthly housing payment.
Two things to know about Bilt Cash: it expires on December 31 of the year you earn it (only $100 rolls over), and you need it in your account before the housing payment — no retroactive rewards.
The family math
Take a $2,500/month mortgage — $30,000 a year that currently earns nothing.
- At 1x: 30,000 Bilt points per year.
- At 1.25x: 37,500 points per year.
Bilt points transfer 1:1 to 25 airline and hotel partners, including World of Hyatt and Alaska Airlines. At typical valuations, 30,000 Bilt points is worth roughly $600+ in travel — and a single Hyatt free night at a Category 1–4 property runs 15,000–18,000 points. Your mortgage alone could fund one to two free family hotel nights a year, on money you were spending anyway.
The catches
You have to actually use the card. The housing earn rate is tied to your everyday Bilt card spending — this isn’t a set-it-and-forget-it mortgage autopay. If you won’t put real spend on the card, the math falls apart.
Housing payments now go by ACH, not card charge. Under the old system, rent rode on the card with a grace-period float. Now Bilt pulls housing payments via bank transfer. No fees, but no float either.
The mortgage rollout has been bumpy. Early users reported payments flagged as non-housing, delayed processing, and in some cases money debited but not reaching the servicer for two weeks. If you set this up, make your first payment well before the due date and keep your old payment method active until at least one payment clears cleanly. A late mortgage payment is not worth any amount of points.
Which card for a family?
If the mortgage play is the whole point, Bilt Blue at $0 is enough — you get the no-fee housing payments and up to 1x without paying for perks you won’t use. Step up to Obsidian if your family spends heavily on dining or groceries and the 3x offsets the $95. Palladium only makes sense if you want a premium travel card anyway; don’t buy it just for the extra 0.25x on housing.
The bottom line
For years, the standard advice was “you can’t earn points on a mortgage.” That’s no longer true — and for a family, the mortgage is the single largest lever in the entire points game. Thirty thousand points a year on spend that used to earn zero is the kind of thing that turns “we can’t afford that trip” into a long weekend at a Hyatt.
Just do it carefully: start early, keep a backup payment method, and make sure you’ll actually use the card enough to unlock the rate. Points are great. On-time mortgage payments are better.
Can you earn credit card points on mortgage payments?
Yes — the Bilt card lets you earn points on mortgage payments, which was previously impossible with mainstream rewards cards. Your mortgage is likely your biggest monthly bill, so the points add up.
Is there a fee for paying your mortgage with Bilt?
Check Bilt’s current terms before applying — fee structures on mortgage payments can change, and the math only works if the points you earn outweigh any cost.
Leave a Reply