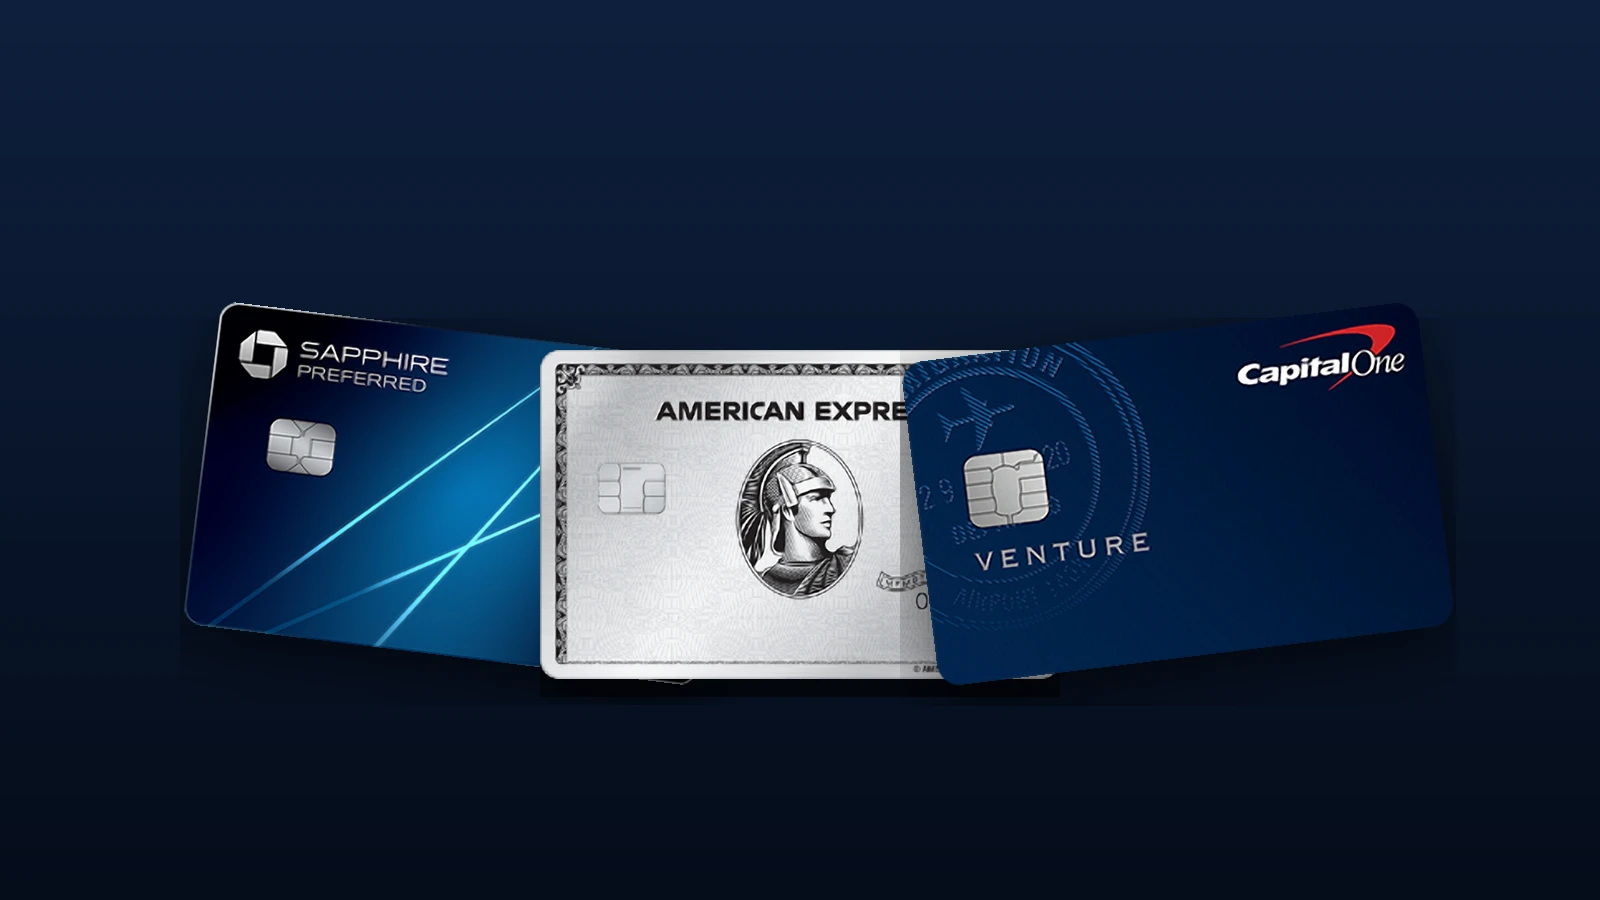
Quick answer: For most families in October 2026, the Chase Sapphire Preferred is the best bonus: 75,000 points for $5,000 in three months on a $95 card. Those points transfer to Hyatt and United, where family redemptions live.
Welcome bonuses are the fastest way to earn points — one application can be worth more than a year of regular spending. But October 2026’s headline numbers come with real spend requirements, and not every big bonus fits a family budget.
Here’s what’s actually on the table this month, ranked by what a family of four can realistically earn and use.
The short list
| Card | Bonus | Spend requirement | Annual fee |
|---|---|---|---|
| Chase Sapphire Preferred | 75,000 UR points | $5,000 / 3 months | $95 |
| Chase Sapphire Reserve | 100,000 UR points | $6,000 / 3 months | $795 |
| Capital One Venture | 75,000 miles + $300 travel credit | $4,000 / 3 months | $95 |
| Amex Platinum | Up to 175,000 MR points | $12,000 / 6 months | $895 |
| Amex Gold | Up to 100,000 MR points | $8,000 / 6 months | $325 |
| IHG One Rewards Premier Select | 200,000 IHG points | $5,000 / 3 months | $350 |
| Capital One Venture X | 75,000 miles | $4,000 / 3 months | $395 |
| Air France KLM Visa Signature | 70,000 miles + 100 XP | $3,000 / 90 days | $89 |
Best for most families: Chase Sapphire Preferred
75,000 Ultimate Rewards points for $5,000 in three months, on a $95 card. That’s the best effort-to-reward ratio on this list. $5,000 over three months is ~$1,667/month — groceries, gas, and bills get most families there without trying.
The points transfer 1:1 to Hyatt and United, which is exactly where family redemptions live. At ~1.6¢ per Hyatt point, this bonus is worth roughly $1,200 in hotel stays.
The premium play: Chase Sapphire Reserve
100,000 points for $6,000 in three months. Bigger bonus, bigger fee ($795), and a meaningfully harder spend requirement. Only take this one if your natural spending clears $2,000/month and you’ll actually use the travel credits and lounge access. The math works for traveling families; it’s a money-loser as a drawer card.
The easy $95: Capital One Venture
75,000 miles plus a $300 hotel/vacation-rental credit through Capital One Travel, for $4,000 in three months. The $300 credit alone covers three years of the $95 fee. Venture miles are simple — redeem against any travel purchase — which makes this the lowest-fuss bonus here.
The high roller: Amex Platinum (up to 175,000 points)
The biggest number on the board, with two catches: the offer varies by applicant (check yours before assuming 175K), and $12,000 in six months is serious spending. That’s $2,000/month every month for half a year. For a family with real monthly spend — mortgage-adjacent bills, childcare, groceries — it’s reachable. For everyone else, it’s a trap that ends in manufactured spending.
The hotel play: IHG Premier Select (200,000 points)
The new $350 IHG card’s launch bonus: 200,000 points for $5,000 in three months. At ~0.5¢ per IHG point, that’s roughly $1,000 in hotel value — enough for 4–6 nights at family-friendly IHG properties. Pairs naturally with the card’s 4th-night-free benefit.
The quiet value: Air France KLM Visa (70,000 miles)
Easiest spend requirement on this list — $3,000 in 90 days — and Flying Blue miles are quietly one of the best currencies for family award travel to Europe. 70,000 miles covers a lot of distance at Flying Blue’s promo-reward pricing.
Business cards worth knowing
If you have any side income — freelancing, reselling, the Etsy shop — business cards don’t count against Chase’s 5/24 rule the same way, and October’s business offers are historically strong:
- Ink Business Preferred: 100,000 UR for $8,000/3mo ($95 fee)
- Ink Business Cash / Unlimited: $1,000 cash back each — record highs, no annual fee
- Amex Business Platinum: up to 300,000 MR for $20,000/3mo ($895 fee) — enormous, but that spend requirement is a full-time job
The family rules for chasing bonuses
1. Never spend extra to earn a bonus. If the requirement exceeds your natural spending, skip the card. Manufactured spending turns a “free” bonus into an expensive hobby.
2. One bonus at a time. Stagger applications 2–3 months apart. Overlapping spend requirements is how people end up buying things they don’t need in month three.
3. Know the guardrails. Chase won’t approve you for most cards if you’ve opened 5+ cards in 24 months (the 5/24 rule). Amex welcome bonuses are once per lifetime per card — you can’t cancel and re-earn later.
4. The bonus is the beginning, not the end. A 75,000-point bonus is worth ~$1,200 at Hyatt. But only if you actually book the Hyatt. Points sitting in an account earn nothing.
The bottom line
October 2026 is a genuinely strong month — the Sapphire Preferred at 75K, Venture’s 75K + $300 credit, and the IHG 200K launch bonus are all top-tier offers with reachable spend requirements. Pick the one whose spending you’d do anyway, hit the requirement with your normal bills, and put the points toward the next family trip.
What is the best credit card signup bonus in October 2026?
For most families, the Chase Sapphire Preferred — 75,000 Ultimate Rewards points for $5,000 in three months on a $95 card. The points transfer 1:1 to Hyatt and United, and the spend requirement fits normal family budgets.
How much do you have to spend to earn a credit card welcome bonus?
It varies widely: from $3,000 in 90 days (Air France KLM Visa) to $12,000 in six months (Amex Platinum). Only apply if your natural spending — groceries, bills, gas — covers the requirement without extra purchases.
Can you earn a welcome bonus more than once on the same card?
Generally no. Amex restricts welcome bonuses to once per lifetime per card product. Chase doesn’t officially do once-per-lifetime, but its 5/24 rule (no approvals if you’ve opened 5+ cards in 24 months) limits churning.
Do business credit cards count against Chase 5/24?
Most business cards (including Chase’s own Ink cards and Amex business cards) don’t appear on your personal credit report, so they don’t add to your 5/24 count. But Chase still applies 5/24 when deciding whether to approve you.
Leave a Reply